
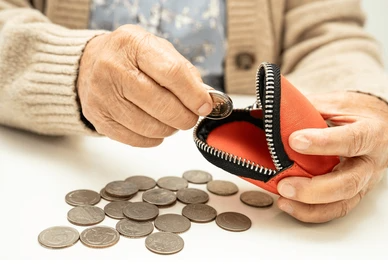
INDIANA – For five straight years, more older Americans have slipped into poverty, and the primary safety net keeping even more of them afloat is facing a shrinking countdown.
The poverty rate for Americans 65 and older jumped to 15.4% in 2025, reaching the highest level of any age group, according to the U.S. Census Bureau’s annual poverty report. Up from 9.4% in 2020, this figure represents over 10 million older adults living below the poverty threshold.
Seniors mark the only demographic whose poverty rate has continuously climbed every year since 2020. While other age groups experienced a brief dip in 2021 before creeping back up, the rise among seniors stands as the largest increase across all demographics.
Understanding the Supplemental Poverty Measure
These statistics are drawn from the Supplemental Poverty Measure (SPM). Unlike the official poverty rate, the SPM factors in noncash government benefits while deducting necessary out-of-pocket expenses such as taxes, work costs, and medical expenditures. Policy analysts widely regard the SPM as a more precise tool for evaluating poverty trends and measuring the real-world impact of government assistance.
Across the entire U.S. population, the overall SPM rate edged up slightly from 13.0% to 13.1%.
Despite the worsening numbers, government data underscores that the situation would be far worse without Social Security.
“Social Security benefits decreased the SPM rate by 8.5 percentage points, lifting 28.8 million people above the poverty line,” the Census Bureau noted in its report. The agency identified Social Security as the nation’s single largest antipoverty program in 2025, noting that seniors made up over 70% of those rescued from poverty by the program—amounting to 20.9 million individuals.
This spike in senior poverty coincides with an urgent timeline for lawmakers in Washington.
The Old-Age and Survivors Insurance (OASI) Trust Fund, which supplements payroll tax revenue to pay out monthly retirement benefits, is now projected to exhaust its reserves in the fourth quarter of 2032, according to the latest Social Security Board of Trustees report.
For 16 consecutive years, the retirement program’s expenditures have outpaced incoming payroll taxes, requiring the government to draw down trust fund reserves to cover the difference. While previous estimates indicated the fund would last until 2033, the depletion timeline was accelerated to late 2032 following tax changes enacted under the One Big Beautiful Bill Act. The legislation introduced temporary additional standard deductions for taxpayers over 65, ultimately reducing the volume of tax revenue funneled back into the trust fund from Social Security benefit taxation.
The Cost of Inaction
Should Congress fail to pass corrective solvency legislation before the 2032 deadline, the program will legally be restricted to paying out only what it collects through real-time tax revenue.
- Automatic Cuts: An immediate, across-the-board benefit reduction of 22% would take effect for all current and future beneficiaries.
- Monthly Impact: According to estimates from the nonprofit Committee for a Responsible Federal Budget, this cut would translate to an average loss of roughly $500 per month for beneficiaries.
As living costs, healthcare expenses, and housing continue to strain fixed budgets, advocacy groups warn that allowing the trust fund to dry up would trigger unprecedented financial disruption for millions of vulnerable older Americans.